








PFA deductible expenses 2026: what you deduct from income and how much they cut your taxes
Which expenses a PFA on the real income system deducts in 2026, and how much they actually cut your income tax, CASS and CAS.

What to remember
- On the real income system, in 2026, you deduct from your income the expenses made for your activity, paid in the same year and proved with an invoice or receipt in the PFA's name. On the income norm you deduct nothing.
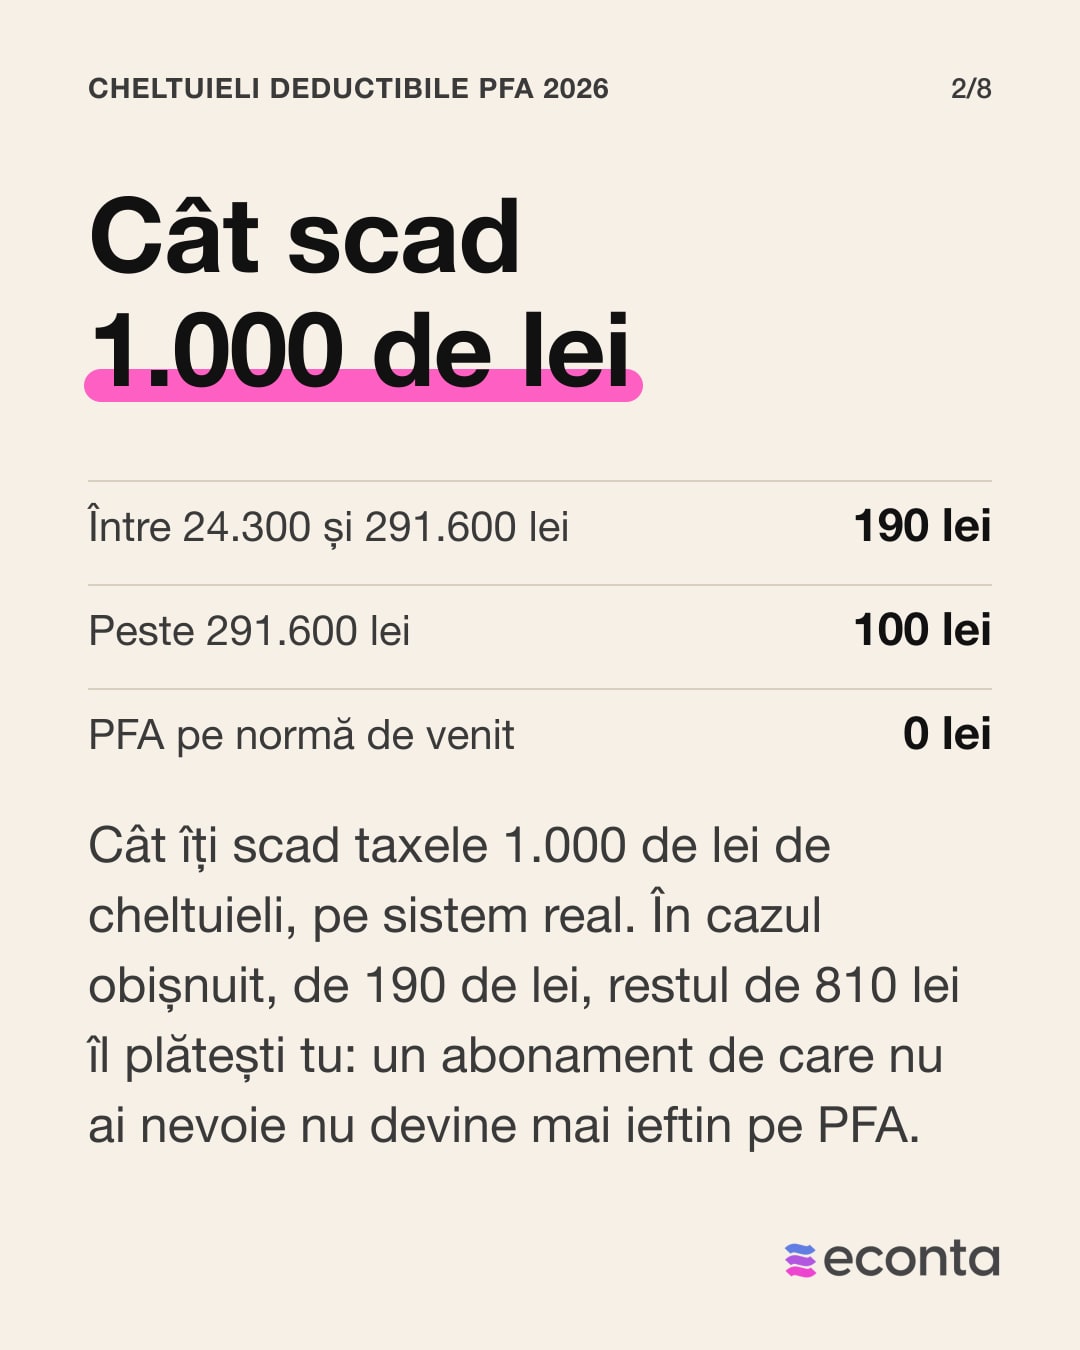
- 1,000 RON of expenses cuts your taxes by about 190 RON: 100 RON of CASS and 90 RON of income tax, as long as your net income stays between 24,300 and 291,600 RON. Below or above these thresholds only the income tax drops, by 100 RON.
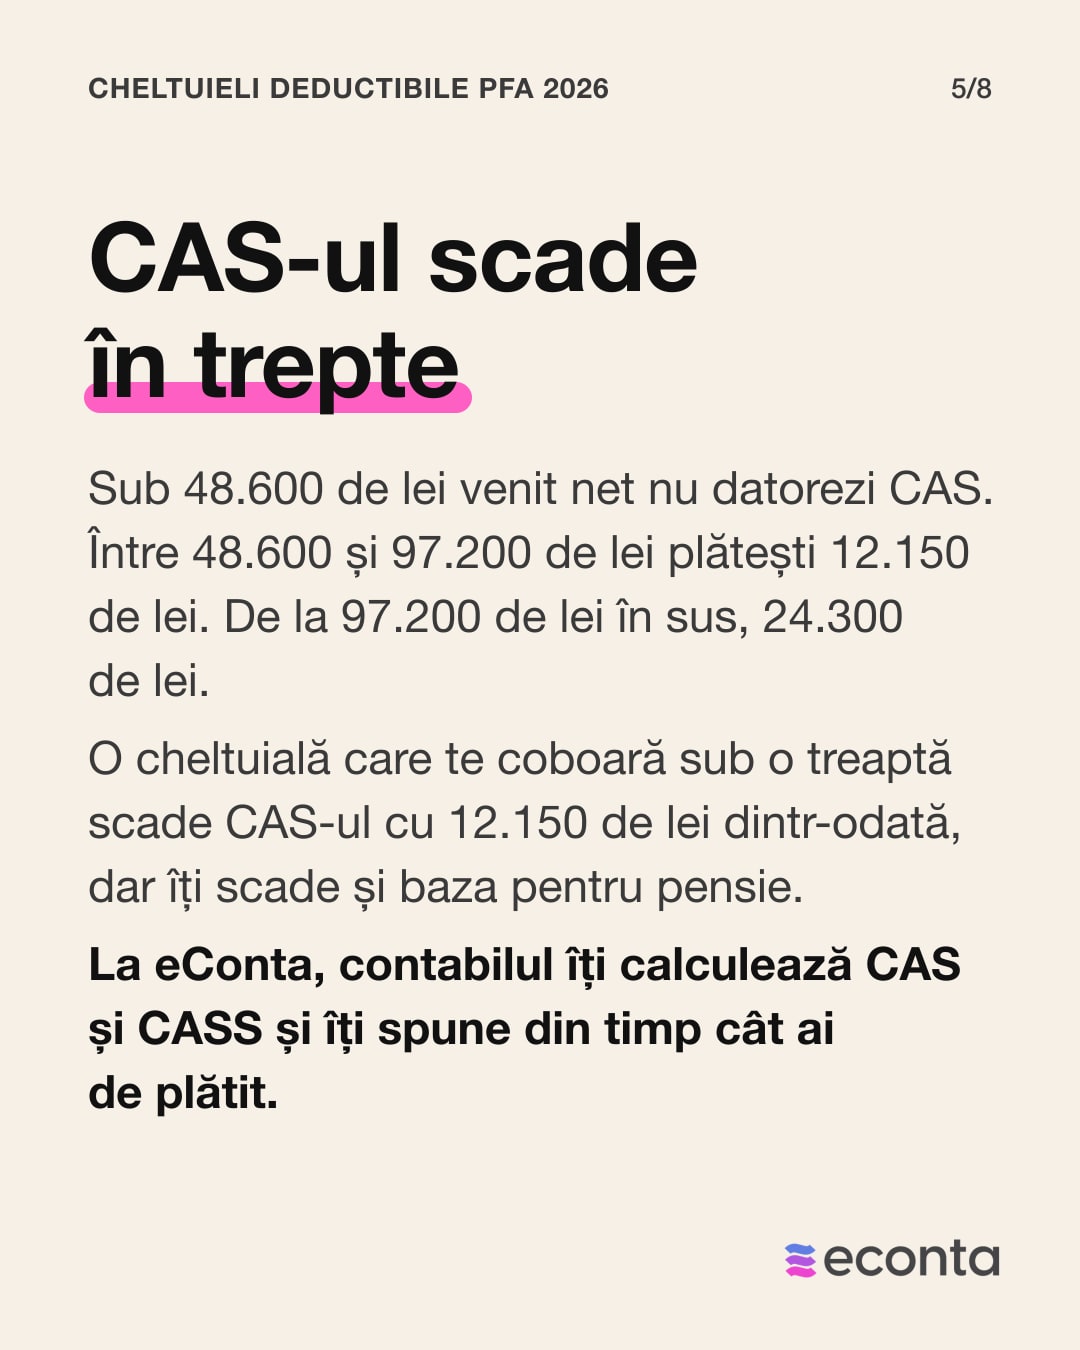
- CAS (the pension contribution) does not drop RON for RON: it stays at 12,150 or 24,300 RON a year and only goes down when your net income falls below 97,200 or below 48,600 RON.
- Limits: a car also used privately is deducted at 50%, only one car, business entertainment up to 2%, voluntary pension and health insurance up to 400 € a year each, and assets from 5,000 RON are depreciated. Sponsorships and donations are not deducted.
- At eConta: your dedicated CECCAR-certified accountant checks which expenses you can deduct and which documents you need, and the Single Tax Return is included in PFA accounting, from 39 €/month.
PFA deductible expenses are the expenses made for your activity that, if you work on the real income system (sistem real), you deduct from your income before income tax and CASS (health insurance contribution) are calculated. In 2026, a deductible expense of 1,000 RON cuts your taxes by about 190 RON, not by 1,000, and CAS (social security contribution) moves only in steps. To see what you pay with your own expenses, use the SRL vs PFA tax calculator.
The figures apply to income earned in 2026, with thresholds calculated on the gross minimum wage of 4,050 RON, declared in the Single Tax Return (Form 212) by 25 May 2027 (updated on 11.11.2026). Below you find what an expense cuts depending on your income, the list by category, the limits and a worked example.
| Your net income per year (2026) | What 1,000 RON of expenses cuts | What you save |
|---|---|---|
| Below 24,300 RON (6 gross minimum wages) | Only the income tax. CASS stays at the minimum of 2,430 RON. | 90 RON |
| Between 24,300 RON and 291,600 RON, without going below a CAS threshold | CASS by 100 RON and income tax by 90 RON | 190 RON |
| Above 291,600 RON (72 gross minimum wages) | Only the income tax. CASS is capped at 29,160 RON. | 100 RON |
| The expense takes you below 97,200 RON | CAS goes down from 24,300 RON to 12,150 RON | 11,125 RON (from 98,000 to 97,000 RON net) |
| PFA on the income norm (norma de venit) | Nothing: taxes are calculated on the norm | 0 RON |
Which expenses a PFA can deduct on the real income system
A PFA on the real income system deducts any expense made for the activity, paid in that year and proved with a document in the PFA’s name, under Article 68(4) of the Fiscal Code. An expense paid in December 2026 counts for 2026. An invoice received in December and paid in January counts for 2027.
| Category | Examples | Document you need |
|---|---|---|
| Equipment under 5,000 RON | monitor, phone, peripherals, software licences and subscriptions | invoice in the PFA’s name |
| Equipment from 5,000 RON | a laptop of 7,000 RON | invoice, then depreciation over several years |
| Space | office rent, coworking, the part of your home used for the activity | contract and invoice or receipt |
| Utilities, phone, internet | only the part used for the activity | invoice |
| Services | accountant, bank and platform fees, hosting, advertising | invoice or bank statement |
| Training | courses, conferences, specialist books | invoice |
| Travel | transport and accommodation for the activity | invoice and the travel document |
| Insurance | professional risk insurance, insurance of business assets | policy and proof of payment |
How much PFA deductible expenses cut from your taxes
An expense of 1,000 RON lowers your net income by 1,000 RON. Your taxes then drop by 10% CASS and by 10% income tax on what remains after CASS, which is 190 RON. You pay the other 810 RON yourself, so a subscription you do not need does not become cheaper just because you put it on the PFA.
CAS works differently, in fixed steps. Below 48,600 RON of net income you owe no CAS. Between 48,600 RON and 97,200 RON you pay 12,150 RON. From 97,200 RON upwards you pay 24,300 RON, under Article 148 of the Fiscal Code. An expense that takes you below a step cuts CAS by 12,150 RON at once, but it also lowers the base for your pension.
Hypothetical example: an IT PFA with 10,000 RON a month and 2,000 RON of expenses
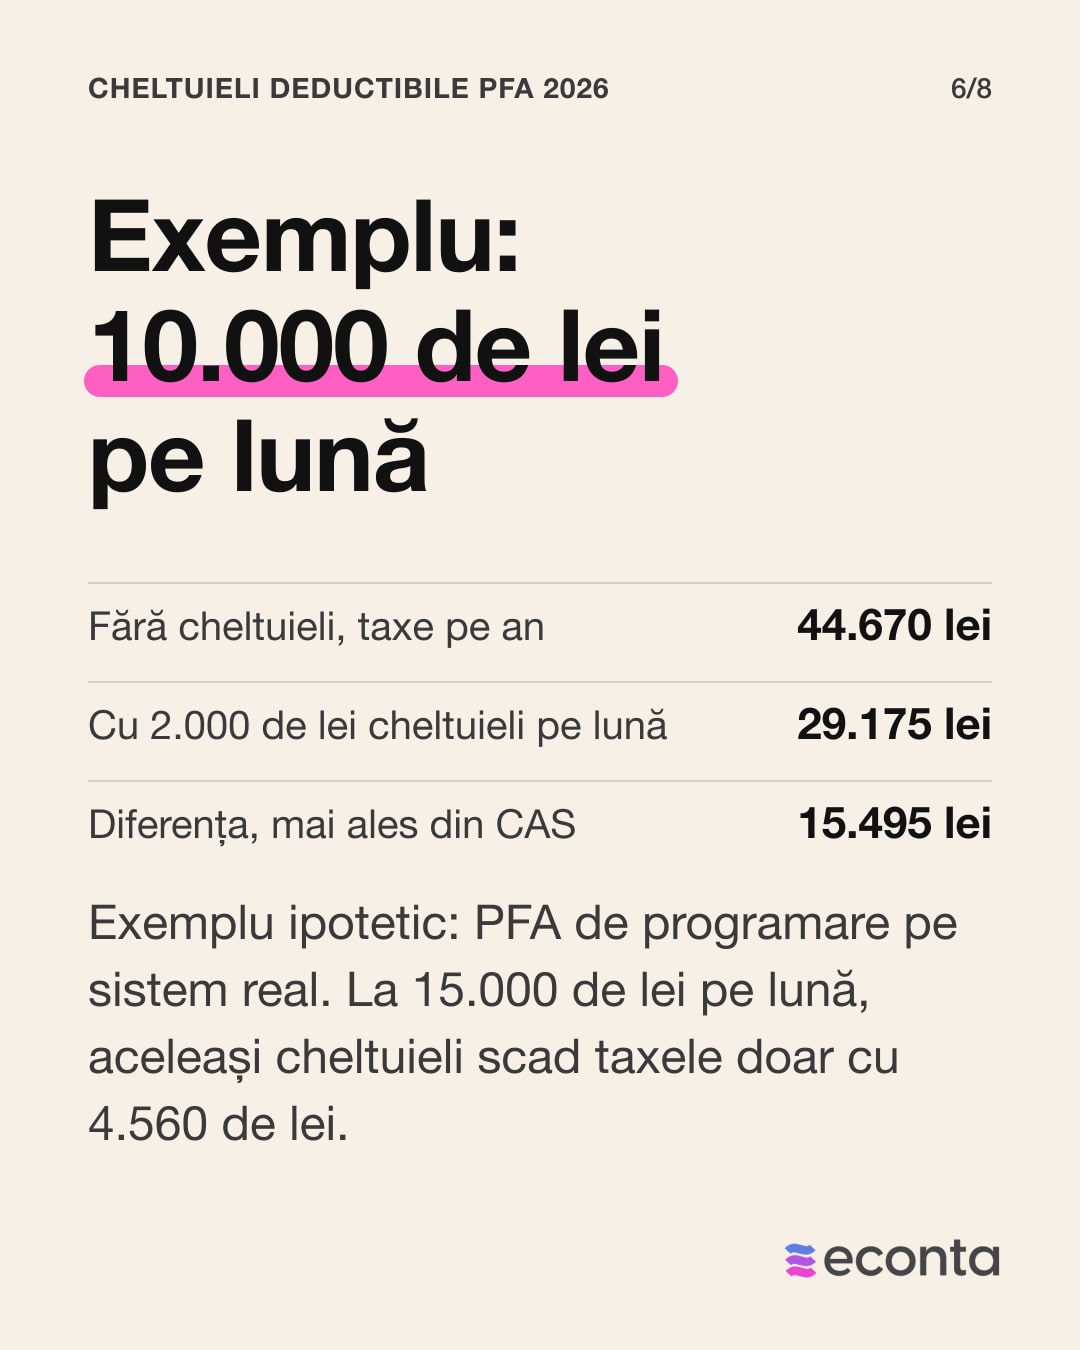
Assumptions: a programming PFA on the real income system, with income of 10,000 RON a month (120,000 RON a year), no other income, not employed and not a pensioner. The calculation uses the same rules as the SRL vs PFA tax calculator.
Without expenses, net income is 120,000 RON and taxes come to 44,670 RON a year: CAS 24,300 RON, CASS 12,000 RON and income tax 8,370 RON. With 2,000 RON of expenses a month, net income drops to 96,000 RON, below the 97,200 RON threshold, and taxes fall to 29,175 RON: CAS 12,150 RON, CASS 9,600 RON and income tax 7,425 RON. The difference, 15,495 RON a year, comes mostly from the CAS step.
The same calculation at 15,000 RON a month gives a saving of only 4,560 RON on the same 24,000 RON of expenses, because net income stays above 97,200 RON and CAS does not move. The answer to the forum question (“with 2,000 RON of expenses a month, would CASS go down?”) is yes, by 10% of the expenses, as long as net income stays above 24,300 RON.
Limited PFA deductible expenses: the car, business entertainment, pension
A car that is also used privately is deducted at 50%, and a PFA can count only one car per person, under Article 68(5)(j) and (7)(k). The depreciation of a passenger car is deducted at most 1,500 RON a month. The exception is cars used for paid passenger transport, such as Uber and Bolt, which have no 1,500 RON cap (Article 28(14)(c), applied to a PFA through Article 68(4)(d)). Business entertainment (meals with clients, gifts) counts up to 2% of the calculation base. Voluntary pension and voluntary health insurance count up to the equivalent of 400 € a year each, and a gym subscription up to 100 € a year.
Assets of 5,000 RON or more, used for over a year, are fixed assets and are deducted through depreciation, not all at once. A phone, internet and home utilities that you also use privately are deducted only for the part linked to the activity.
PFA deductible expenses for Bolt, Uber and doctors
A Bolt or Uber driver with a PFA on the real income system deducts in full the costs of the car used for paid passenger transport (fuel, service, insurance), plus the platform commission, based on the commission invoice. For the returns you file as a driver, see accounting for ridesharing drivers.
A doctor with an individual medical practice or a PFA deducts malpractice insurance, consumables, equipment (through depreciation) and the fee to the College of Physicians, the latter up to 5% of gross income.
What is not deductible, even with an invoice
PFA deductible expenses do not include those for personal or family use, donations, sponsorships, fines and penalties, loan instalments and income tax, under Article 68(7) of the Fiscal Code. An invoice in your personal ID number (CNP) does not make an expense deductible if the item is not used in the activity.
What nobody tells you
Assets bought on the PFA and kept by you when you close the PFA count as income, at market price. The laptop you deducted today can become taxable income in three years, at closing or when you move to an SRL.
Going below a CAS step looks good in the Single Tax Return, but it also lowers your pension record. You can declare a CAS base higher than the minimum if you want a higher pension.
What to do now
- By 31 December 2026, pay from the PFA account the expenses you want in 2026: the payment date decides the year.
- Ask for an invoice in the PFA’s name at every purchase for the activity, so that it counts as a PFA deductible expense.
- Record income and payments monthly in the journal register and keep the tax records register.
- Before a big purchase, check in the SRL vs PFA tax calculator whether you are close to a CAS threshold.
- By 25 May 2027, file the Single Tax Return for your 2026 income.
If you want someone to tell you every month what you can deduct and how much to set aside, PFA accounting at eConta starts from 39 €/month, with the Single Tax Return included.
Frequently asked questions
Does CASS go down in the Single Tax Return if I have deductible expenses on a PFA?
Yes. CASS is 10% of net income, and every 1,000 RON of expenses cuts it by 100 RON, as long as net income stays between 24,300 RON and 291,600 RON. Below 24,300 RON you pay the minimum of 2,430 RON, whatever your expenses.
Can I put my laptop on the PFA, or is it a fixed asset?
Yes, if you use it for the activity and the invoice is in the PFA’s name. Below 5,000 RON you deduct it in full in the year of payment. From 5,000 RON upwards you depreciate it over several years.
Can I deduct the rent or utilities of the flat where I work?
Yes, only for the part of the home used for the activity, with a document that shows the space made available to the PFA. Your accountant tells you which document you need and what proportion is accepted.
What deductible expenses does a PFA on the income norm have?
None. On the income norm, taxes are calculated on the fixed amount of the norm, and expenses change nothing. If you have large expenses, compare the norm with the real income system in the SRL vs PFA tax calculator.
Sources
- Parliament of Romania, Law 227/2015 on the Fiscal Code, Article 68(4), (5), (6), (7), (7^1), (8) (net income from independent activities, deductible, limited and non-deductible expenses), consolidated version published by ANAF, accessed on 31.10.2026. https://static.anaf.ro/static/10/Anaf/legislatie/Cod_fiscal_norme_2023.htm
- Same law, Article 28(2)(b) and (14) (the fixed asset threshold, depreciation of passenger cars), accessed on 31.10.2026.
- Same law, Article 148 (CAS base, 12 and 24 minimum wages) and Article 170 (CASS base, at most 72 minimum wages), accessed on 31.10.2026.
- Same law, Article 135^1(3) (the minimum wage for thresholds: the one in force on 1 January). https://legislatie.just.ro/Public/DetaliiDocument/171282
- eConta, PFA tax calculator (the same rules as the examples), 31.10.2026. https://www.econta.ro/calculator-taxe-pfa/
- Real questions from forums (paraphrased):
- PFA with 10,000 RON a month: if I have 2,000 RON of expenses every month, does CASS go down? · r/RoFiscalitate2, February 2026
- How much do I save if I buy the laptop on a company, an SRL or a PFA? · r/RoFiscalitate2, December 2025
- Are subscriptions from EU providers (GitHub and others) deductible? · r/RoFiscalitate2, January 2026
A question about your PFA?
How eConta helps with your PFA
Related articles
-
 Tax and ANAF
Invoice to a foreign client without VAT: what to write on it and what to file
Four cases, four invoices: an EU company with a valid VIES number, an EU company without one, a non-EU company and a private individual, with the return that follows each.
Updated: 11 November 2026 · 16 min read -
 Tax and ANAF
SAF-T (Form D406) return: a legal obligation and a responsible approach
At eConta, SAF-T costs 15 €, and the checking is included. Your peace of mind too.
Updated: 9 July 2025 · 5 min read -
 Tax and ANAF
The tax regime for micro-enterprise income tax
This article explains the tax regime for micro-enterprises in Romania, including the eligibility conditions, the rates of…
Updated: 24 February 2025 · 6 min read