Law 239/2025: share capital, dividends and loans to shareholders
Practical summary of Law 239/2025: minimum SRL share capital by turnover, and new rules for dividends and loans to shareholders.
1) Share capital of an SRL: new rules, based on turnover
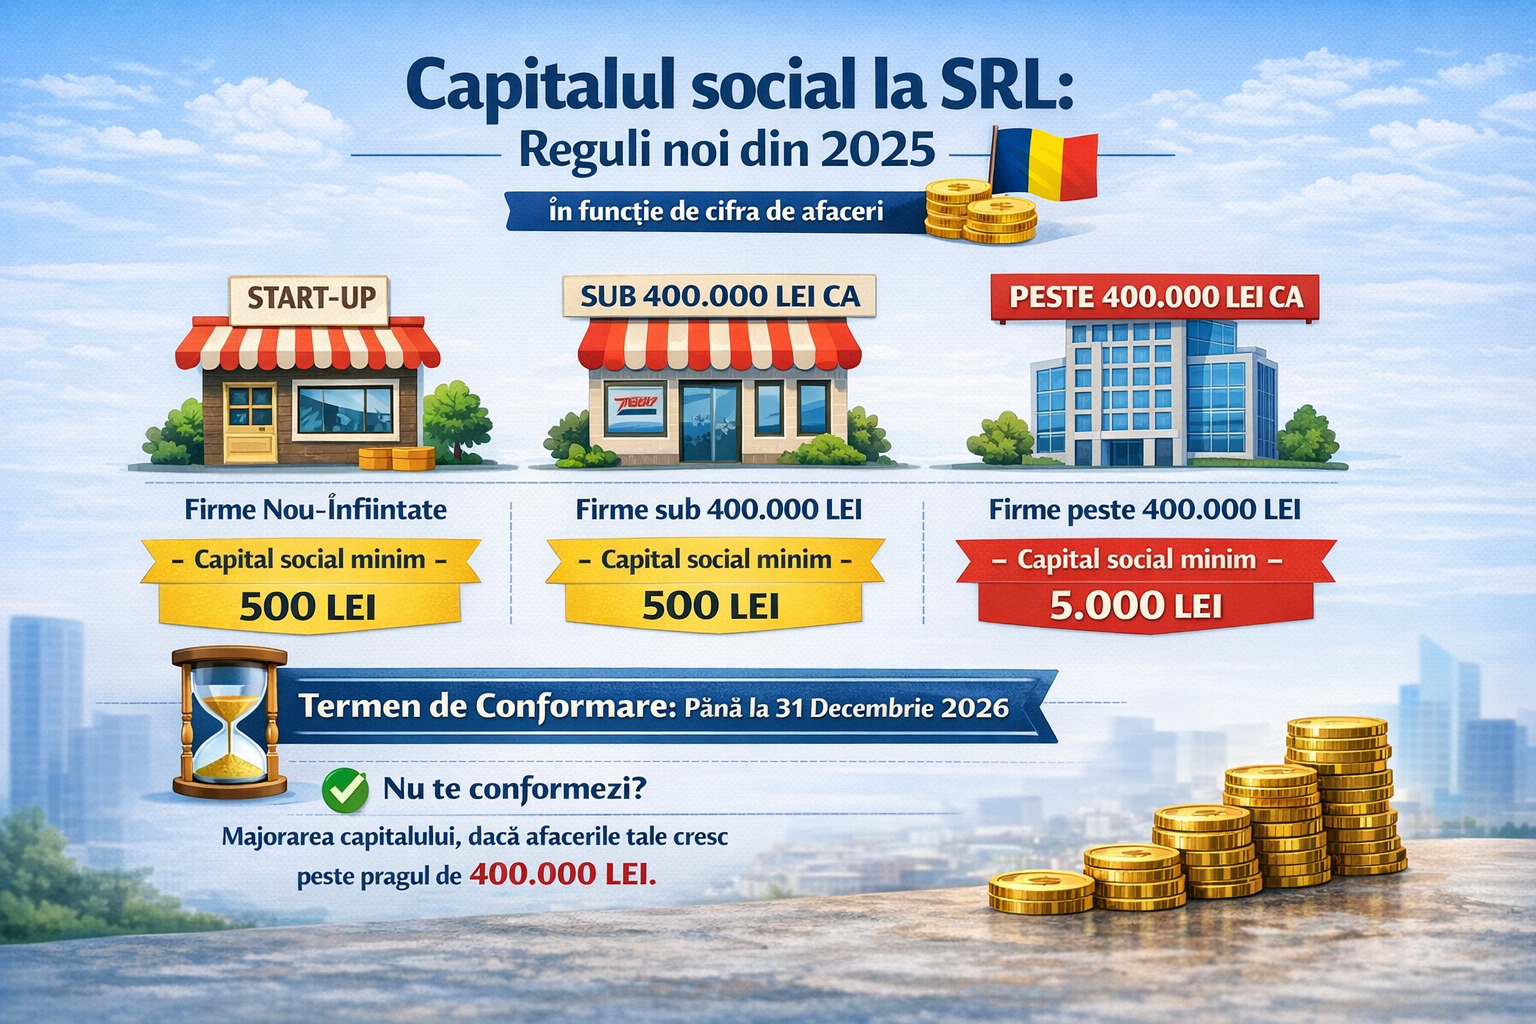
Law no. 239/2025 brings important changes to the minimum share capital of a limited liability company (SRL). The key rule: the thresholds depend on turnover. Growing companies must pay attention when they pass 400,000 RON.
The new thresholds
- Newly set up companies: minimum share capital 500 RON
- Companies with turnover below 400,000 RON: minimum share capital 500 RON
- Companies with turnover above 400,000 RON: minimum share capital 5,000 RON
Important: If you already have a company and your turnover has not passed 400,000 RON, you do not have to increase the capital. When you pass the threshold, you have until the end of the following year to comply.
What you risk if you do not comply
- possible penalties
- in serious cases, judicial dissolution
Recommendation: if you are getting close to the 400,000 RON threshold, plan the capital increase in advance (decision of the general meeting of shareholders, updating the documents, filing with the Trade Register (ONRC)).
2) Dividends and loans to shareholders: much stricter rules
The legislative package adds restrictions on the financial relationship between the company and its shareholders. They apply especially to interim dividends, loans to shareholders and the conditions related to net assets.
What is no longer allowed (in short)
- Loans to shareholders before the interim dividends are settled.
- Distributing dividends if net assets are below half of the share capital.
- Distributing dividends if there are carried-forward losses that are not covered.
Key rule: if there is profit in the current year but also a carried-forward loss, dividends can be distributed only after the loss is fully covered and after the required reserves are set up.
Restoring net assets
If net assets fall below half of the share capital, the company must take steps to restore them within a set period. Until it complies, distributing dividends becomes risky or forbidden, depending on the situation.
Fines and liability
- fines between 10,000 and 200,000 RON for not following the rules
- possible joint and several liability for budget obligations, in certain cases
Recommendation: before dividends or loans to shareholders, check with your accountant: net assets, carried-forward losses and mandatory reserves.
Want to check your company’s situation quickly?
In eConta, your accountant can follow the relevant indicators (profit/loss, reserves, net assets). They can guide you so you avoid blockages or risks with dividends and loans.
Note: This material is for information only. It does not replace accounting or legal advice applied to your case.
Need help?
Leave us a number and an accountant will call you.
Thank you!
We got your details. We'll call you.
How eConta helps with Law 239
Related articles
-
 Money and dividends
The tax regime for micro-enterprise income tax
This article explains the tax regime for micro-enterprises in Romania, including the eligibility conditions, the rates of…
Updated: 24 February 2025 · 6 min read -
 Company setup
How to set up an SRL in Romania in 2026: a complete step-by-step guide
You fill in a form, the rest is simple.
Updated: 5 June 2026 · 16 min read -
 Tax and ANAF
SAF-T (Form D406) return: a legal obligation and a responsible approach
At eConta, SAF-T costs 15 €, and the checking is included. Your peace of mind too.
Updated: 9 July 2025 · 5 min read